Guide to Can Foreigners Get a Mortgage in Israel?
 Buying property in Israel has become increasingly popular among international buyers, Jewish immigrants, investors, and foreign citizens seeking a second home in the country. One of the most common questions asked by overseas purchasers is: Can Foreigners Get a Mortgage in Israel?
The simple answer is yes. Foreign citizens can obtain financing from Israeli banks, although the process differs from that faced by Israeli residents. Understanding the requirements, restrictions, available loan options, and mortgage approval process is essential before purchasing real estate in Israel.
Whether you are purchasing an apartment in Jerusalem, a beachfront property in Netanya, a luxury home in Herzliya, an investment apartment in Tel Aviv, or a family residence in Beit Shemesh, understanding Can Foreigners Get a Mortgage in Israel can help you make informed financial decisions and avoid costly mistakes.
This guide explains everything foreign buyers need to know about Israeli mortgages, including eligibility requirements, loan-to-value ratios, documentation, currency options, interest rates, approval procedures, and practical tips for securing financing.
Understanding the Israeli Mortgage Market
Before answering Can Foreigners Get a Mortgage in Israel, it is important to understand how the Israeli mortgage system works.
Unlike some countries where mortgage lending is heavily standardised, Israeli mortgages often consist of multiple loan tracks combined into one mortgage package. Borrowers can divide their mortgage into fixed-rate, variable-rate, CPI-linked, and non-linked portions.
Israeli banks evaluate each applicant individually based on:
- Income
- Assets
- Existing debts
- Credit history
- Property value
- Country of residence
- Ability to repay
Foreign buyers are generally viewed as a higher risk than Israeli residents because their income is earned abroad and enforcement can be more complex if repayment problems occur.
Nevertheless, most major Israeli banks actively lend to foreign buyers.
Can Foreigners Get a Mortgage in Israel?
The direct answer to Can Foreigners Get a Mortgage in Israel is yes.
Many foreign citizens successfully obtain mortgages from Israeli banks every year.
Eligible applicants include:
- American citizens
- British citizens
- Canadian citizens
- French citizens
- Australian citizens
- South African citizens
- European Union citizens
- Foreign residents planning aliyah
- Overseas investors
Israeli banks routinely finance purchases by non-residents.
However, approval is never automatic. Foreign applicants must meet stricter documentation requirements than Israeli residents.
The bank must verify:
- Identity
- Income
- Employment
- Assets
- Creditworthiness
- Ability to repay
Because documentation originates outside Israel, the approval process may take longer than for local borrowers.
Which Israeli Banks Offer Mortgages to Foreigners?
Several major Israeli banks regularly work with international buyers.
Common lenders include:
- Bank Leumi
- Bank Hapoalim
- Mizrahi-Tefahot Bank
- Discount Bank
- First International Bank of Israel
Among these institutions, many mortgage professionals consider Mizrahi-Tefahot Bank particularly active in the mortgage sector.
Each bank has its own underwriting policies and may offer different terms depending on the borrower’s profile.
This is why many foreign purchasers use Israeli mortgage brokers to compare options.
How Much Can Foreigners Borrow?
One of the most important aspects of Can Foreigners Get a Mortgage in Israel is understanding borrowing limits.
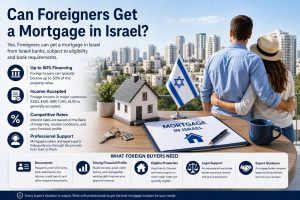
Israeli banking regulations generally allow foreign buyers to finance up to approximately 50% of the property’s value.
In some cases, borrowers with exceptionally strong financial profiles may receive slightly better financing terms.
Typical financing ranges include:
|
Buyer Type |
Typical Maximum Financing |
|
Foreign resident investor |
50% |
|
Future olim with documented plans |
Sometimes higher |
|
Israeli resident |
Up to 75% (depending on circumstances) |
Example:
Property Purchase Price:
4,000,000 NIS
Maximum Foreign Mortgage:
2,000,000 NIS
Required Equity:
2,000,000 NIS plus taxes and costs
This means foreign buyers should be prepared with substantial available capital before beginning their property search.
What Documents Are Required?
When asking Can Foreigners Get a Mortgage in Israel, documentation is often the biggest challenge.
Israeli banks generally require:
Identification Documents
- Passport
- Additional government-issued identification
- Proof of address
- Tax identification number
Employment Verification
For salaried employees:
- Employment letter
- Recent payslips
- Tax returns
- Bank statements
For self-employed applicants:
- Accountant letters
- Business financial statements
- Tax returns
- Corporate documents
Banking Records
Banks commonly request:
- Three to twelve months of statements
- Investment account records
- Savings account statements
Credit Reports
Foreign applicants are usually asked to provide:
- Credit reports from their home country
- Credit scores where available
American applicants may provide:
- FICO reports
- Experian reports
- Equifax reports
British applicants may provide reports from UK credit agencies.
Income Requirements
Another key factor in Can Foreigners Get a Mortgage in Israel is income.
Israeli banks evaluate:
- Stability of earnings
- Income history
- Debt obligations
- Future earning prospects
Most lenders prefer:
- Consistent employment history
- Reliable income streams
- Strong savings
- Manageable debt levels
The bank typically calculates a debt-to-income ratio to determine affordability.
Monthly mortgage obligations generally should not exceed a reasonable percentage of monthly income.
Applicants with strong earnings from:
- Professional careers
- Businesses
- Investments
- Rental income
often receive more favourable consideration.
Can Foreigners Use Foreign Income?
Yes.
One of the most important answers to Can Foreigners Get a Mortgage in Israel is that foreign-earned income is generally acceptable.
Israeli banks regularly approve borrowers whose income comes from:
- United States
- United Kingdom
- Canada
- France
- Australia
- South Africa
- Europe
Accepted income sources may include:
- Salaries
- Self-employment income
- Company ownership
- Pension income
- Rental income
- Investment income
Banks usually require extensive documentation proving the source and consistency of earnings.
The more transparent the financial records, the smoother the approval process.
Which Currencies Are Accepted?
Foreign buyers often wonder whether they must earn income in shekels.
Fortunately, when considering Can Foreigners Get a Mortgage in Israel, the answer is no.
Israeli banks commonly accept income denominated in:
- US Dollars
- British Pounds
- Euros
- Canadian Dollars
- Australian Dollars
However, exchange-rate risk becomes a major factor.
For example:
A borrower earning dollars but paying a shekel mortgage may experience higher effective payments if exchange rates move unfavourably.
This currency exposure should be carefully evaluated before choosing a mortgage structure.
Mortgage Approval Process
Understanding the approval process is critical when evaluating Can Foreigners Get a Mortgage in Israel.
The process usually follows several stages.
Stage 1: Preliminary Assessment
The bank reviews:
- Income
- Assets
- Debts
- Credit profile
Stage 2: Property Evaluation
The bank examines:
- Purchase contract
- Property location
- Property value
- Appraisal report
Stage 3: Underwriting
The bank analyses:
- Risk factors
- Repayment capacity
- Documentation
Stage 4: Mortgage Offer
The borrower receives:
- Interest rates
- Loan structure
- Payment schedule
Stage 5: Closing
The mortgage is finalised and funds are released according to the purchase agreement.
Popular Cities for Foreign Buyers Seeking Mortgages
When discussing Can Foreigners Get a Mortgage in Israel, location often influences financing decisions.
Popular destinations include:
Jerusalem
Jerusalem remains one of the strongest markets for foreign purchasers.
Many buyers come from:
- United States
- United Kingdom
- France
Neighbourhoods frequently attracting overseas buyers include:
- Baka
- German Colony
- Rehavia
- Arnona
- Talbiya
- Katamon
- Old Katamon
Netanya
Netanya continues attracting:
- French buyers
- British retirees
- Investors
The coastal lifestyle and established international communities make financing applications common.
Beit Shemesh
Many Anglo families purchase homes in:
- Ramat Beit Shemesh
- Sheinfeld
- Nofei Aviv
Israeli banks are accustomed to reviewing mortgage applications from overseas purchasers in this market.
Tel Aviv
Foreign investors frequently purchase:
- Luxury apartments
- Rental investments
- Vacation properties
Because of high property values, financing requirements can be substantial.
Herzliya
Luxury international buyers often seek financing for homes and apartments near the coast.
The city’s strong demand continues attracting foreign capital.
Interest Rates for Foreign Buyers
When evaluating Can Foreigners Get a Mortgage in Israel, interest rates play a major role in determining the overall affordability of the purchase.
Foreign buyers often assume they will automatically receive significantly higher rates than Israeli residents. While non-residents may sometimes pay slightly more due to perceived lending risk, the difference is not always substantial.
Mortgage rates are influenced by:
- The Bank of Israel interest rate
- Global financial markets
- Inflation expectations
- Loan-to-value ratio
- Borrower’s financial profile
- Currency exposure
- Mortgage track selection
A borrower with strong income, excellent credit history, substantial assets, and a large down payment may receive more favourable terms than a borrower with weaker financial credentials.
Banks generally evaluate the entire financial picture rather than relying solely on residency status.
Fixed Rate Mortgages for Foreign Buyers
A fixed-rate mortgage offers stability because the interest rate remains unchanged for the agreed period.
Benefits include:
- Predictable monthly payments
- Protection against future rate increases
- Easier budgeting
- Reduced financial uncertainty
For many overseas buyers purchasing holiday homes, retirement properties, or long-term family residences, fixed-rate mortgages provide peace of mind.
When discussing Can Foreigners Get a Mortgage in Israel, fixed-rate products are often attractive because foreign buyers may already face exchange-rate uncertainty between their home currency and the Israeli shekel.
Variable Rate Mortgages for Foreign Buyers
Variable-rate mortgages fluctuate according to market conditions.
Potential benefits include:
- Lower initial interest rates
- Greater flexibility
- Potential savings if rates decline
Potential disadvantages include:
- Rising monthly payments
- Interest-rate risk
- Budgeting challenges
Foreign buyers should carefully assess whether they can comfortably manage payment increases if rates rise.
Mixed Mortgage Structures
Israeli mortgages are unique because borrowers can combine multiple mortgage tracks.
For example:
- 40% fixed-rate
- 30% prime-linked
- 30% variable-rate
This approach allows buyers to balance:
- Security
- Flexibility
- Cost
- Risk
Many mortgage professionals recommend a diversified mortgage structure rather than placing the entire loan in a single track.
This flexibility is one reason why the answer to Can Foreigners Get a Mortgage in Israel is more attractive today than ever before.
Can Future Olim Get Better Mortgage Terms?
A common question related to Can Foreigners Get a Mortgage in Israel concerns future immigrants.
Individuals planning aliyah sometimes receive more favourable treatment than foreign investors.
Benefits may include:
- Higher financing percentages
- Special mortgage programmes
- Government assistance programmes
- Reduced purchase tax rates after aliyah
Banks often evaluate:
- Aliyah plans
- Immigration timeline
- Employment prospects in Israel
- Long-term residency intentions
Future olim should consult both a mortgage broker and a lawyer to understand available incentives.
Government Assistance Programmes
Certain government-backed programmes may be available to qualifying borrowers.
Eligibility can change over time and often depends upon:
- Citizenship status
- Family size
- Residency status
- Property location
Because regulations change periodically, buyers should verify current programmes before relying on projected benefits.
Using a Mortgage Broker
One of the smartest steps for foreign buyers is working with an experienced mortgage broker.
When analysing Can Foreigners Get a Mortgage in Israel, a mortgage broker can provide substantial advantages.
Benefits include:
- Access to multiple banks
- Comparison of loan offers
- Negotiation of interest rates
- Assistance gathering documentation
- Guidance through the approval process
- English-language support
Foreign buyers often discover that different banks provide very different offers for the same borrower.
A broker may help identify the most suitable lender and mortgage structure.
Why Documentation Matters
Israeli banks tend to be documentation-driven.
Many mortgage delays occur because:
- Documents are missing
- Tax returns are incomplete
- Statements are unclear
- Foreign documents require translation
Proper preparation can dramatically improve approval speed.
Typical supporting documents may require:
- Apostille certification
- Notarised translation
- Certified copies
Having these documents ready before beginning the mortgage process can save weeks or months.
Property Types Eligible for Mortgages
When discussing Can Foreigners Get a Mortgage in Israel, it is important to understand which properties are typically eligible.
Banks commonly finance:
- Apartments
- Private homes
- Duplexes
- Penthouses
- New construction units
- Investment properties
Financing may be more complicated for:
- Agricultural properties
- Commercial properties
- Unregistered structures
- Certain inherited properties
- Properties with planning irregularities
Before signing a contract, buyers should confirm that the property can be financed.
New Construction Purchases
Foreign buyers frequently purchase apartments from developers.
These “off-plan” or “on-paper” purchases are common in:
- Jerusalem
- Netanya
- Beit Shemesh
- Ashdod
- Herzliya
- Tel Aviv
Banks generally finance such purchases, although the mortgage may be released in stages according to construction progress.
This allows buyers to spread payments over several years.
Tax Considerations for Foreign Buyers
While exploring Can Foreigners Get a Mortgage in Israel, buyers must also consider taxation.
Important taxes and costs may include:
Purchase Tax
Purchase tax rates for foreign buyers are generally higher than those applicable to many Israeli residents.
The exact amount depends on:
- Property value
- Residency status
- Ownership history
Because tax rates periodically change, buyers should obtain updated calculations before committing to a purchase.
Legal Fees
Most buyers hire an Israeli real estate lawyer.
Legal fees commonly cover:
- Contract review
- Due diligence
- Registration procedures
- Mortgage registration
Bank Fees
Mortgage-related expenses may include:
- Appraisal fees
- Registration fees
- Document certification fees
- Bank processing charges
These costs should be included when calculating the total cash requirement.
Common Challenges Foreign Buyers Face
Although the answer to Can Foreigners Get a Mortgage in Israel is yes, foreign applicants often encounter challenges.
Exchange Rate Risk
A buyer earning dollars but repaying a shekel mortgage faces currency fluctuations.
For example:
If the dollar weakens against the shekel, mortgage payments effectively become more expensive.
Currency planning should therefore be part of every financing strategy.
Documentation Delays
Many applications stall because documents are:
- Missing
- Outdated
- Incomplete
- Improperly translated
Careful preparation can prevent unnecessary delays.
Different Banking Standards
Foreign buyers are often surprised by the amount of documentation required by Israeli banks.
Requirements may differ significantly from:
- American banks
- British banks
- Canadian lenders
- European institutions
Patience and organisation are essential.
How to Improve Mortgage Approval Chances
Understanding Can Foreigners Get a Mortgage in Israel is only the first step. Maximising approval chances is equally important.
Maintain Strong Credit
A strong credit history demonstrates responsible financial management.
Banks prefer borrowers who:
- Pay debts on time
- Maintain low debt levels
- Have established credit histories
Increase Your Down Payment
Larger down payments generally improve:
- Approval odds
- Interest rates
- Financing flexibility
The lower the lender’s risk, the more attractive the borrower becomes.
Reduce Existing Debt
High debt levels may negatively affect affordability calculations.
Reducing unnecessary obligations before applying can strengthen an application.
Organise Documentation Early
Gathering documents in advance can significantly accelerate approval.
Prepare:
- Tax returns
- Payslips
- Bank statements
- Credit reports
- Asset statements
before beginning property negotiations.
Frequently Asked Questions
Can Foreigners Get a Mortgage in Israel Without Israeli Citizenship?
Yes. Israeli citizenship is not required. Many foreign nationals obtain mortgages from Israeli banks every year.
Can Foreigners Get a Mortgage in Israel While Living Abroad?
Yes. Many borrowers remain overseas throughout the mortgage approval process.
Can Foreigners Get a Mortgage in Israel for Investment Property?
Yes. Financing is commonly available for investment purchases, although down payment requirements are generally higher.
Can Foreigners Get a Mortgage in Israel in US Dollars?
Most mortgages are denominated in shekels, although various financing structures may be available depending on the bank and the borrower’s circumstances.
Can Foreigners Get a Mortgage in Israel Before Making Aliyah?
Yes. Many future immigrants purchase property before relocating to Israel.
Can Foreigners Get a Mortgage in Israel if Self-Employed?
Yes. Self-employed applicants are commonly approved, although they usually face additional documentation requirements.
How Long Does Mortgage Approval Take?
Simple applications may receive preliminary approval within days, while complex international applications can take several weeks.
Is a Mortgage Broker Necessary?
Not legally. However, many foreign buyers benefit significantly from professional mortgage guidance.
Final Conclusion: Can Foreigners Get a Mortgage in Israel?
The answer to Can Foreigners Get a Mortgage in Israel is clearly yes. Israeli banks regularly provide financing to foreign citizens purchasing residential property throughout the country. Whether buying in Jerusalem, Tel Aviv, Netanya, Herzliya, Ra’anana, Modiin, Beit Shemesh, Haifa, Ashdod, or other Israeli cities, mortgage financing is generally available to qualified overseas buyers.
However, obtaining financing requires preparation. Foreign applicants should expect stricter documentation requirements, larger down payments, detailed income verification, and careful review of their financial position. Most foreign buyers can typically finance up to approximately 50% of a property’s value, making adequate capital reserves essential.
The most successful borrowers approach the process strategically. They organise financial documents early, maintain strong credit profiles, seek professional legal advice, and often work with experienced mortgage brokers who understand both Israeli banking requirements and the unique challenges faced by international purchasers.
Ultimately, Can Foreigners Get a Mortgage in Israel is not simply a question of eligibility. It is a question of preparation, financial strength, and choosing the right financing structure. With proper planning, foreign buyers can successfully secure Israeli mortgage financing and purchase property that supports their personal, family, investment, or aliyah goals for many years to come.