Guide to How to Calculate True ROI on Israeli Investment Properties
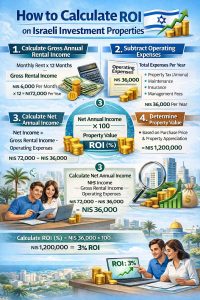 Understanding how to calculate true ROI on Israeli investment properties is not optional if capital preservation matters. Israeli property markets are structurally different from most Western markets: high acquisition friction, low headline yields, regulatory complexity, and currency exposure. Superficial “gross yield” calculations are misleading. This guide explains how to calculate true ROI on Israeli investment properties properly, using conservative assumptions and Israel-specific costs that many investors ignore until it is too late.
Overview & Key Concepts
Explanation
ROI is often treated as a single number. That is already a flawed premise in the context of calculating ROI on real estate investments. When analysing how to calculate true ROI on Israeli investment properties, ROI must be broken into cash yield, capital appreciation, and risk exposure. Israeli residential property typically underperforms on cash yield but compensates through long-term price growth, leverage, and inflation linkage.
Another critical concept is time-weighted return. Israeli property rewards patience. Short holding periods (<5 years) are punished by transaction costs and tax drag. Long holding periods reduce friction but increase exposure to regulatory and demographic shifts.
Key data points
- Median holding period for investors: 8–10 years
- Transaction friction round-trip (buy + sell): 12%–18%
- Inflation linkage on many mortgages: CPI + interest
- Typical annual rent increases: 1%–3%, often below inflation
Practical implications
Anyone serious about how to calculate true ROI on Israeli investment properties must model returns annually, not just at exit. Front-loaded taxes mean early ROI is usually negative. Break-even often occurs years later, even in rising markets.
Examples relevant to Israel
An investor buying in 2020 and selling in 2023 may show a nominal profit but a negative real ROI after taxes, inflation, and lost opportunity cost.
Pricing, Costs & Financial Breakdown
Explanation How to Calculate True ROI on Israeli Investment Properties
This is where theoretical ROI becomes real. How to calculate true ROI on Israeli investment properties requires separating accounting profit from economic profit. Economic profit accounts for capital tied up, inflation erosion, and alternative returns foregone.
Costs are not static. Maintenance rises faster in older buildings, especially without long-term sinking funds (va’ad bayit reserves), impacting the total investment. Renovations are not optional in competitive rental markets.
Key data points
Annual hidden costs often missed:
- Appliance replacement cycles: every 5–7 years
- Major building repairs (roof, plumbing): unpredictable but inevitable
- Management time or fees: even self-managed units have a cost
Financing impact:
- CPI-linked loans can increase principal owed
- Early repayment penalties affect exit ROI
Practical implications
If your spreadsheet assumes flat expenses over 10 years, your ROI model is already wrong. Properly modelling how to calculate true ROI on Israeli investment properties means stress-testing cost inflation, not assuming stability.
Examples relevant to Israel
A Haifa apartment in an older building may require ₪80,000–₪120,000 in capital repairs over a decade. Ignoring this turns a marginal ROI negative.
Risks, Limitations & Critical Notes
Explanation
ROI without risk context is meaningless. How to calculate true ROI on Israeli investment properties must include downside scenarios, not just base cases.
Key structural risks include:
- Government intervention in investor taxation can significantly affect the return on investment for real estate investors.
- Localised oversupply from urban renewal projects
- Demographic stagnation in peripheral cities
- Liquidity risk during geopolitical stress
Key data points
- Investor tax policy has shifted four times since 2015
- Urban renewal has suppressed rents in some neighbourhoods
- Peripheral cities show higher yields but slower liquidity
Practical implications
High yield often signals high risk. Peripheral markets may offer 4%–5% gross yields, but exit liquidity can vanish during downturns. True ROI discounts for this risk.
Examples relevant to Israel
Investors in speculative renewal zones sometimes face years of construction disruption, tenant turnover, and stagnant rents before any appreciation materialises.
Comparison & Practical Recommendations
Explanation
To understand how to calculate true ROI on Israeli investment properties, you must compare like-for-like. Residential property should be evaluated against leveraged and unleveraged alternatives to accurately calculate ROI.
Key comparison metrics:
- Net return after tax
- Volatility and drawdown risk
- Liquidity
- Management burden
Key data points
- Equities outperform property long-term on average
- Property offers leverage with lower margin-call risk
- Real estate provides inflation hedging but poor diversification
Practical implications
If your primary goal is yield, Israeli residential property is usually the wrong tool for achieving high rental yield. If your goal is capital preservation, inflation hedging, or jurisdictional exposure, ROI should be assessed accordingly to ensure profitability.
Examples relevant to Israel
Many foreign investors accept low cash ROI because the property anchors assets in Israel. That is a strategic choice, not a financial optimisation.
Buyer / Homeowner Checklist
Explanation
This checklist operationalises how to calculate true ROI on Israeli investment properties and forces discipline before committing capital.
Key data points
Confirm in writing:
- Worst-case cash flow scenario
- Total tax exposure on exit
- Sensitivity to rent stagnation
- Ability to hold through downturns
- Opportunity cost versus alternatives
- Alignment with personal risk tolerance is crucial for real estate investors when considering return on investment.
Practical implications
If the investment only works assuming uninterrupted appreciation, it is speculative by definition.
Examples relevant to Israel
Many investors discover too late that selling early locks in a loss, while holding longer exposes them to regulatory risk. ROI planning must account for both.
Financing Structure & Leverage Impact on ROI
Explanation
Any serious discussion of how to calculate true ROI on Israeli investment properties that ignores leverage is incomplete. Israeli investors frequently rely on mortgages not to increase yield, but to access the market at all. This fundamentally changes the ROI equation. Leverage magnifies outcomes in both directions: appreciation boosts equity returns, while interest-rate increases can wipe out cash flow entirely.
Unlike many markets, Israeli mortgages often include CPI-linked components, meaning the loan principal itself can grow over time, affecting the overall return on investment. This creates a scenario where nominal equity increases while real equity stagnates or declines. ROI must therefore be measured on equity invested, not property value.
Another structural issue is amortisation speed. Many Israeli loans are front-loaded with interest, delaying principal reduction. This means that early years show weak equity growth even in appreciating markets.
Practical implications
When calculating how to calculate true ROI on Israeli investment properties, you must model:
- ROI on cash invested, not asset price
- Equity growth net of CPI-linked principal increases
- Cash-flow sensitivity to interest-rate hikes
If ROI only works under stable or falling rates, the investment is fragile. Conservative modelling assumes rate volatility.
Tax Optimisation vs Tax Reality
Explanation
Taxes are not a footnote; they are central to how to calculate true ROI on Israeli investment properties. Many investors underestimate how aggressively taxes compress returns over time. Purchase tax is paid upfront, while capital gains tax is deferred — psychologically minimised, but economically unavoidable.
Israeli capital gains tax is calculated on real profit, adjusted for inflation. This sounds fair but often surprises investors whose nominal gains evaporate after adjustments. Depreciation is limited, and allowable expense deductions are narrower than in many jurisdictions.
Rental income taxation and its implications for profitability also matters. Investors choosing the fixed-rate rental tax may simplify compliance but often pay more over long holding periods.
Practical implications
True ROI must be calculated after tax, not before. If two investments have identical gross returns but different tax treatment, their real ROI diverges materially. Any guide on how to calculate true ROI on Israeli investment properties that does not model multiple tax scenarios is incomplete.
Vacancy, Tenant Risk & Cash-Flow Volatility
Explanation
Vacancy assumptions in rental properties are routinely understated, affecting overall return on investment. In reality, how to calculate true ROI on Israeli investment properties requires acknowledging tenant turnover, arrears, and legal delays. Even in strong markets, one vacant month per year is a conservative baseline.
Tenant quality varies dramatically by city, neighbourhood, and apartment type. Smaller units often churn faster in the context of rental properties. Larger family units carry higher vacancy risk due to affordability constraints. Legal eviction timelines can extend losses significantly.
Cash-flow volatility matters more than average yield when evaluating the profitability of rental properties. A property with stable tenants and lower yield may outperform a higher-yield property with erratic occupancy.
Practical implications
ROI models should use expected value, not best case. That means:
- Modelling vacancy explicitly
- Accounting for rent loss during renovations
- Including legal and mediation costs
Ignoring these factors distorts how to calculate true ROI on Israeli investment properties and leads to false confidence in the return on investment.
Appreciation Assumptions & Market Cycles
Explanation
Most Israeli residential ROI depends on appreciation and the purchase price of the property. This is the most dangerous assumption in how to calculate true ROI on Israeli investment properties and impacts the profitability of real estate investors. Appreciation is cyclical, uneven, and policy-sensitive.
Past appreciation does not guarantee future returns. Some cities experience decade-long stagnation. Others see price spikes followed by flat periods. Urban renewal can suppress prices temporarily while promising long-term gains.
ROI models that bake in constant annual appreciation are speculative by definition. Appreciation should be treated as a scenario, not a certainty.
Practical implications
A defensible ROI calculation works without appreciation. If appreciation occurs, it improves outcomes. If it does not, the investment should still be survivable. This distinction separates investment from speculation.
Liquidity, Exit Timing & Forced Sale Risk
Explanation
Liquidity risk is under-analysed in discussions of how to calculate true ROI on Israeli investment properties. Property is illiquid by nature, but Israeli markets can seize up during uncertainty.
Exit timing affects ROI more than entry timing. A forced sale due to cash-flow stress, tax changes, or personal circumstances can destroy years of paper gains. Selling costs alone can exceed 6%–8%.
ROI must therefore be modelled across multiple exit windows, not just an ideal one.
Practical implications
If ROI only works when selling at peak market conditions, it is not robust. Conservative investors assume imperfect exits and discount ROI accordingly.
Opportunity Cost & Capital Allocation
Explanation
The final component of how to calculate true ROI on Israeli investment properties is opportunity cost. Capital invested in property is capital not deployed elsewhere. This includes:
- Global equities
- Bonds
- Business investment
- Liquidity reserves
Property often underperforms equities on a pure return basis. Its value lies in leverage, tangibility, and inflation linkage — not raw ROI.
Final takeaway How to Calculate True ROI on Israeli Investment Properties
Understanding how to calculate true ROI on Israeli investment properties requires abandoning simplified yield metrics and confronting uncomfortable numbers. True ROI in Israel is often modest, heavily back-loaded, and sensitive to policy and interest rates. That does not make Israeli property irrational — but it does mean it should be treated as a strategic, long-term, risk-aware allocation, not a passive income play.
If your ROI model cannot survive higher rates, flat rents, delayed appreciation, and full taxation, then the issue is not the market. It is the assumptions.
Israel Homes Is a Guide to Finding, Understanding, and Buying Property in Israel